Last Updated: October 2026
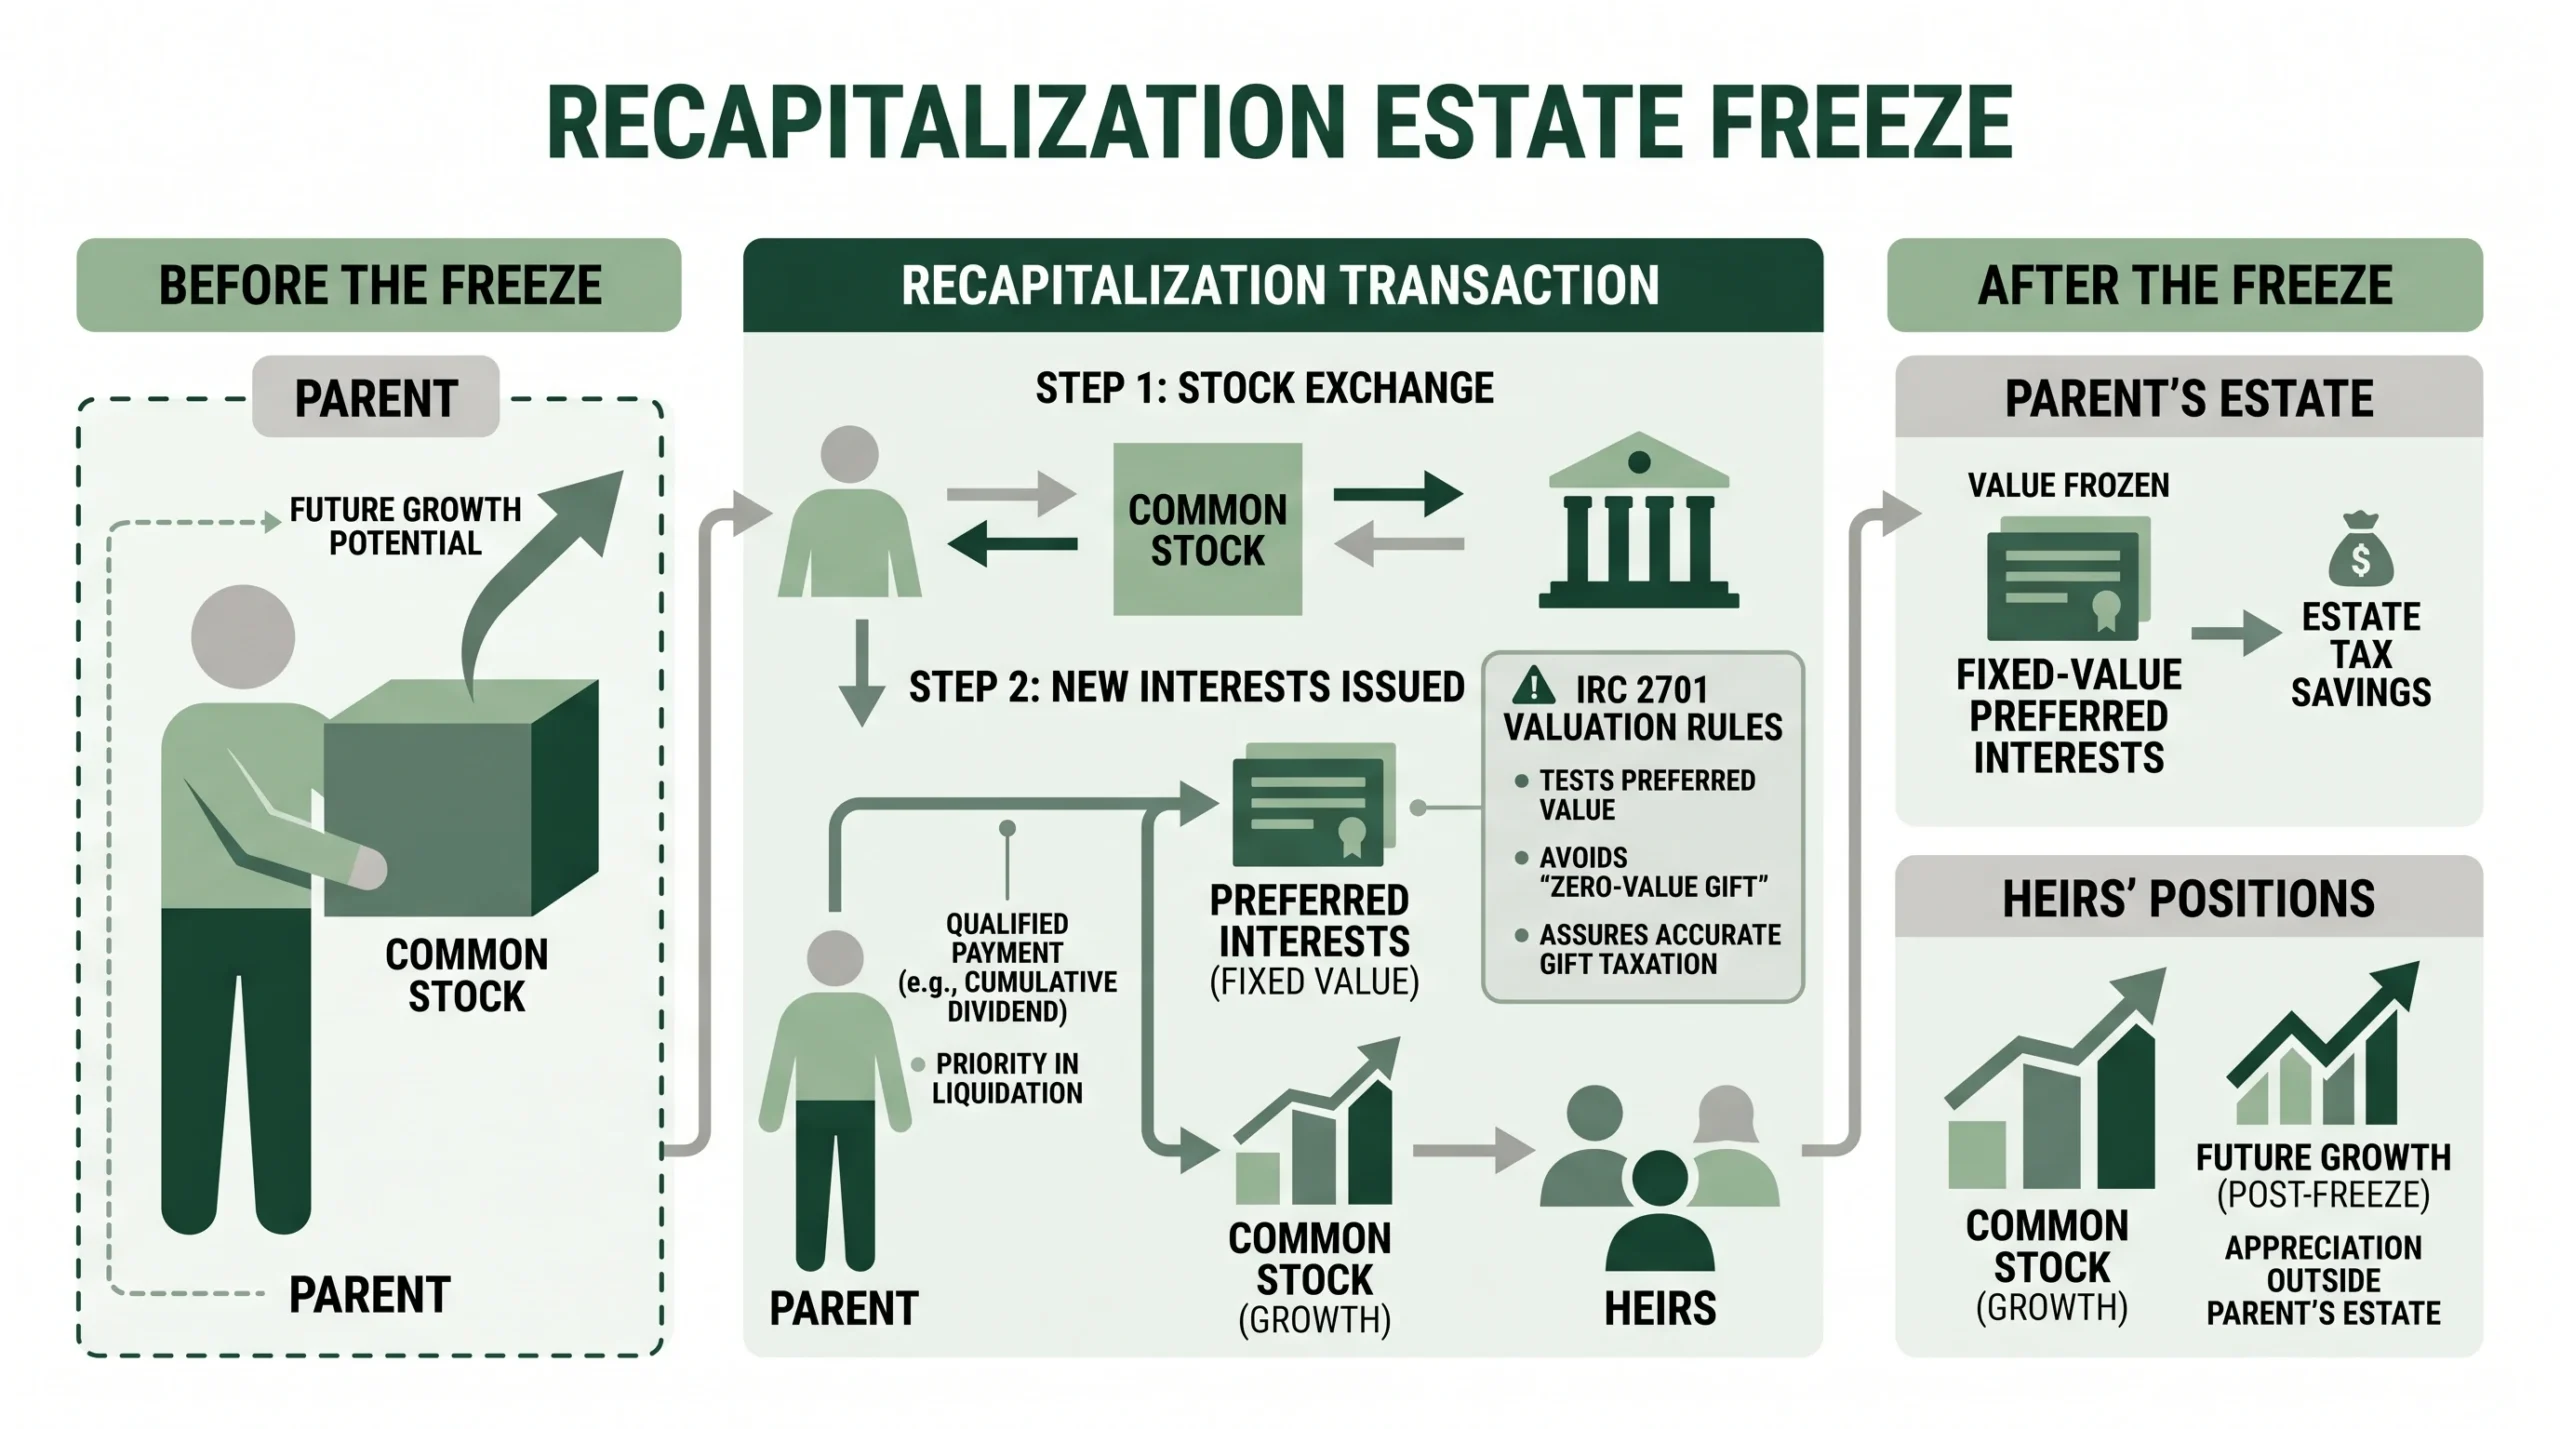
An estate freeze valuation prices the two interests a recapitalization creates, so the IRS sees a sale and not a hidden gift. In an estate freeze, a parent exchanges common stock for a fixed-value preferred interest. The preferred is frozen at today’s value. All future growth shifts to the common stock the children now hold.
The team at Sofer Advisors values these interests for business owners, CPAs, and estate attorneys, backed by Inc. 5000 recognition in both 2024 and 2025. One rule decides the outcome. IRC Section 2701 can value the retained preferred at zero, which inflates the reported gift of the common stock.
This guide explains what an estate freeze is, why the preferred value is frozen, how Section 2701 polices the deal, and how an appraiser values the preferred and the common. It also covers the gift tax exposure when the preferred is priced too high.
Key Takeaways
- What a freeze does: a parent trades common stock for a fixed-value preferred interest, so future growth moves to the common stock held by heirs.
- Why it is frozen: the preferred holds a set value and a set dividend, so the parent’s stake stops growing while the business keeps rising.
- Section 2701 is the gatekeeper: it values the retained preferred at zero unless the preferred carries a qualified payment right.
- Qualified payment is the test: a fixed, cumulative dividend paid on schedule gives the preferred real value and lowers the gift of the common.
- Overvaluing is the risk: price the preferred too high and the IRS cuts it back, taxing a larger gift of the common stock.
Each piece ties into the wider estate plan. The sections below take them one at a time.
Why Does Estate Freeze Valuation Matter?
Estate freeze valuation matters because it decides whether the transfer is taxed as planned or recast as a much larger gift. The parent wants future growth out of the estate at a low tax cost. The freeze does that only if the preferred interest is priced like real senior equity. Price it wrong and the IRS resets the number and adds gift tax.
The stakes are large. Gift tax and estate tax share one graduated rate that climbs to 40 percent at the top. A retained preferred interest that the IRS values at zero can push the reported gift up by millions. That is why the appraisal has to follow Section 2701 from the first step. An appraiser who treats the freeze like an ordinary sale produces a number the IRS will not accept. You can read how an estate freeze locks in today’s value and where the rule bites.
What Is an Estate Freeze?
An estate freeze is a recapitalization that splits a company’s equity into two layers. The parent exchanges common stock for a new preferred interest with a fixed value and a set dividend. The children receive or keep the common stock. From that day on, the preferred stays flat and the common captures all the growth. The parent’s estate is frozen at the preferred’s value.
The appeal is simple. If a company is worth 10 million dollars today and grows to 25 million, the extra 15 million sits in the children’s common stock, outside the parent’s estate. The parent still draws income through the preferred dividend. This is why a freeze suits a growing, income-producing business more than a passive one. The structure runs through a recapitalization, so the entity documents and the share terms have to match the valuation. See our guide to a recapitalization for the mechanics.
How Does Section 2701 Police the Freeze?
Section 2701 is the rule Congress wrote in 1990 to stop abusive freezes. It applies when a senior family member keeps a preferred interest and transfers common equity to the next generation. The default is harsh. The retained preferred is valued at zero unless it carries a qualified payment right. A zero value makes the gift of the common stock much larger on paper.
The escape is the qualified payment. Under the statute, a retained interest counts only if it pays a fixed, cumulative dividend on a set schedule. A non-cumulative dividend is valued at zero unless the holder elects to treat it as qualified. Rights that look like value but may never pay, such as a put or a conversion right, are also valued at zero. The law stops an owner from claiming a rich preferred while taking nothing real out of it. The full text sits at 26 U.S. Code Section 2701.
How Does an Appraiser Value the Preferred Interest?
An appraiser values the preferred interest by pricing its cash flow and its rights as of the transfer date. The core driver is the coupon, the fixed dividend rate the preferred pays. A cumulative dividend that must be made up if missed is worth more than a non-cumulative one. Liquidation rights, put rights, and conversion rights each change the value too.
Two rules shape the math. First, only a qualified payment right carries value under Section 2701, so a non-cumulative coupon drops to zero unless the holder elects otherwise. Second, when a preferred holds both a qualified payment and an extraordinary right like a put, the appraiser must assume the extraordinary right is exercised in the way that gives the lowest total value. The dividend rate should reflect what an outside investor would demand for comparable preferred stock. A thin coupon or a below-market rate is the first thing an examiner challenges, as the special valuation rules make plain. Our guide to valuing preferred interests under Section 2701 walks through the detail.
How Is the Common Stock Valued, and What Is the Gift Tax Risk?
The common stock is valued by subtraction. The appraiser values the whole company, subtracts the value of the retained preferred under Section 2701, and the remainder is the gift of the common. Because the preferred is often valued low or at zero, the common gift can be large. A special floor applies. The junior equity cannot be valued at less than 10 percent of total equity plus certain debt owed to the transferor.
The gift tax risk comes from overvaluing the preferred. If the appraisal assigns the preferred too much value, the common gift looks small, and the IRS will cut the preferred back, often to zero, and tax the difference. A second trap waits later. If the qualified payment dividends are not actually paid, Section 2701 compounds the shortfall and adds it to the estate at death. The fix is a coupon set at a market rate, paid on time, and documented, then reported with adequate disclosure on the gift tax return.
Who Values an Estate Freeze, and How Do the Options Compare?
Owners choose a valuation partner by the size of the interest, the audit risk, and the budget. A freeze valuation needs an appraiser who knows Section 2701 and can document both the preferred and the common for the IRS. Large national firms such as Alvarez & Marsal, Stout, and Kroll serve big public companies with broad advisory teams. Sofer Advisors focuses on family and closely held freezes, with expert witness testimony in 11+ cases and 180+ five-star Google reviews.
| Provider | Typical role | Best for |
|---|---|---|
| Specialized valuation firm (e.g. Sofer Advisors) | Prices the preferred and the common under Section 2701 and documents the gift | Family and closely held freezes needing audit-ready support |
| Large national firm | Broad advisory plus valuation at enterprise scale | Large public companies with complex, multi-entity plans |
| Estate attorney | Drafts the recapitalization and share terms; does not value | Families needing the legal structure built and reviewed |
Sofer Advisors runs each engagement through a four-phase process it calls The Sofer Difference, moving from Discovery to Diligence to Analysis to Delivery. That order keeps the preferred, the common, and every assumption tied to the facts behind them. It reflects the Heart of a Teacher approach, which means explaining the reasoning behind a number instead of just handing over a figure. See how Sofer Advisors approaches estate and gift tax work through its business valuation services.
Frequently Asked Questions
What is an estate freeze?
An estate freeze is a planning move that locks a parent’s business value in place while shifting future growth to the children. The parent exchanges common stock for a fixed-value preferred interest in a recapitalization. The preferred stays flat, and the common stock the heirs hold captures all later appreciation. The goal is to cap the parent’s taxable estate at today’s number. Sofer Advisors values both interests so the transfer holds up for gift and estate tax.
How does an estate freeze work?
A freeze works through a recapitalization. The company creates a senior preferred interest with a fixed value and a set dividend, and the parent trades common stock for it. The children receive or keep the common stock. From that point the preferred value is frozen, and growth builds in the common. The parent still draws income from the preferred dividend. Sofer Advisors prices the preferred and the common as of the exchange date so the gift is reported correctly.
What gets frozen in an estate freeze?
The parent’s interest is what gets frozen. By converting common stock into a fixed-value preferred interest, the parent caps that stake at today’s value, so it no longer grows with the company. Everything above the preferred value flows to the common stock held by the next generation. The estate is frozen, not the business itself, which keeps operating and growing. Sofer Advisors documents the frozen preferred value so it matches the gift tax return and later estate filings.
What is the role of IRC Section 2701?
IRC Section 2701 is the valuation rule that polices estate freezes. It applies when a senior family member keeps a preferred interest and transfers common equity to relatives. The rule values the retained preferred at zero unless it carries a qualified payment right, which makes the gift of the common stock larger. Congress added it in 1990 to curb freeze abuses. Sofer Advisors applies Section 2701 before building the number so the reported gift stands up on audit.
What is a qualified payment under Section 2701?
A qualified payment is a fixed dividend on cumulative preferred stock, paid on a set schedule. Under Section 2701, only a retained interest with a qualified payment right holds value. A non-cumulative dividend is valued at zero unless the holder elects to treat it as qualified. The payment must be made on time, because unpaid amounts are compounded and taxed later. Sofer Advisors tests whether a preferred interest meets the qualified payment standard before valuing it.
How are the preferred and common interests valued?
The preferred is valued first, off its dividend rate, its cumulative or non-cumulative terms, and its liquidation, put, and conversion rights. Section 2701 drops many of those rights to zero. The common is valued by subtraction: the whole company value minus the retained preferred. A floor applies, since the junior equity cannot be valued below 10 percent of total equity plus certain debt. Sofer Advisors builds both sides and reconciles them for the gift tax return.
Is a GRAT a kind of estate freeze?
Yes, a GRAT is one way to freeze value, but it works through a trust rather than a recapitalization. A grantor retained annuity trust pays the parent a fixed annuity for a term, and the growth above that annuity passes to the heirs. Section 2702, not 2701, governs the GRAT. A preferred recapitalization and a GRAT solve the same problem in different ways. Sofer Advisors values business interests for both structures so the reported gift is defensible.
What happens if the preferred interest is overvalued?
If the preferred is overvalued, the gift of the common stock looks too small. On audit the IRS cuts the preferred value back, often to zero under Section 2701, and taxes the larger common gift that results. Interest and penalties can follow, and the plan can unwind. A below-market or unpaid dividend is the usual cause. Sofer Advisors sets the preferred coupon at a market rate and documents it so the value survives IRS review.
How much does an estate freeze valuation cost?
Most estate freeze valuations run from $7,500 to $25,000 and take about four to eight weeks, depending on the entity and the deadline. The range covers valuing the preferred, the common, and the Section 2701 analysis behind the gift. A flat fee is quoted up front, so the cost is clear before work starts. Sofer Advisors scopes the engagement first, then quotes a fixed price. Request a free estimate for your situation.
Related Case Studies
- Chapter 14 Rules: How IRC 2701 and 2703 Affect Family Transfers
- Section 2704 and Family Entity Valuation Discounts
- How Family Limited Partnerships Are Valued for Gift and Estate Tax
Executive Summary
An estate freeze swaps a parent’s common stock for a fixed-value preferred interest, so future growth shifts to the common stock the children hold. The preferred is frozen at today’s value, and the estate is capped there. IRC Section 2701 controls the valuation. It values the retained preferred at zero unless the preferred carries a qualified payment, a fixed cumulative dividend paid on schedule. The common stock is then valued by subtraction, with a floor of 10 percent of total equity. Overvalue the preferred and the IRS resets it, taxing a larger gift. A market-rate coupon, paid on time and documented, is what keeps the freeze a sale instead of a hidden gift.
What Should You Do Next?
Start by listing the business interest you plan to freeze and the entity documents behind it, since the preferred terms drive the whole valuation. Confirm the dividend rate, whether it is cumulative, and the liquidation and put rights before the recapitalization is signed. This guide was prepared by David Hern CPA ABV ASA, founder of Sofer Advisors, an Inc. 5000 firm specializing in neutral third-party valuations for estate and gift tax. Schedule a free consultation through our contact page, or learn more about our business valuation services.
People Also Read
- What Is a GRAT and How Does It Transfer Business Value to Heirs?
- Valuation Discounts (DLOC and DLOM) on Estate and Gift Tax Returns
About the Author
This guide was prepared by David Hern CPA ABV ASA, founder of Sofer Advisors, a business valuation firm headquartered in Atlanta, GA serving clients across the United States. David holds dual accreditations as an Accredited Senior Appraiser (ASA) and is Accredited in Business Valuation (ABV), credentials recognized by the IRS, SEC, and FINRA. He also holds the Certified Exit Planning Advisor (CEPA) designation. With 15+ years of valuation experience, David has served as an expert witness in 11+ cases across multiple jurisdictions and built Sofer Advisors into an Inc. 5,000-recognized firm with 180+ five-star Google reviews. Its full W2 employee team maintains subscriptions to all major valuation databases and operates under a next business day response policy.
For professional business valuation services, visit soferadvisors.com/about-us/ or contact Sofer Advisors at soferadvisors.com/contact-us/.
This content is for informational purposes only and does not constitute professional valuation advice. Business valuation conclusions depend on specific facts and circumstances. Contact Sofer Advisors for guidance regarding your specific situation.