Last Updated: August 2026
A business with $2 million in revenue is typically worth about $600,000 to $6 million. The exact figure rests on profit, not sales. Most firms this size sell for a few times their adjusted earnings. Per recent private-company deal data, private firms change hands on profit and risk, not top-line revenue. Sofer Advisors values each firm on its own numbers, not a rule of thumb.
Owners ask this question before a sale, a partner buyout, a gift or estate filing, or a bank loan, and the answer drives real decisions. Because two firms with identical sales can be worth very different amounts, guessing from revenue alone is risky. A supported figure, built on adjusted earnings and market evidence, gives an owner a number they can act on.
Key Takeaways
- Profit drives value: Buyers pay for earnings, not sales. A $2M firm is priced on its adjusted profit.
- A realistic range: Most sell for a few times earnings, often $600,000 to $6 million.
- SDE versus EBITDA: Smaller owner-run firms use SDE. Larger, manager-run firms use EBITDA.
- Add-backs matter: Normalized earnings remove owner perks and one-time costs. That lifts the base for value.
- Revenue is a weak anchor: Two firms with $2M in sales can be worth very different amounts.
These points share one theme: value follows earning power, not the top line. The sections below show how appraisers turn $2 million in sales into a defensible number you can stand behind.
Why Is Revenue a Weak Value Anchor?
Revenue is a weak anchor because a buyer pays for profit, not sales. Two firms can both post $2 million in revenue. One keeps $200,000 in profit. The other keeps $600,000. The second is worth far more. Revenue shows how much money comes in. It says nothing about what stays after costs. Appraisers look past the top line to the cash an owner truly takes home.
That cash figure carries most of the weight in any business valuation. A high sales number can hide thin margins, heavy debt, or high overhead. When an appraiser studies your books, the first job is to find real earnings. From there, the fair market value follows. This is why two firms with the same sales rarely fetch the same price. What lies under the revenue decides the result, and revenue alone tells you little about it.
What Is a Realistic Value Range at $2M?
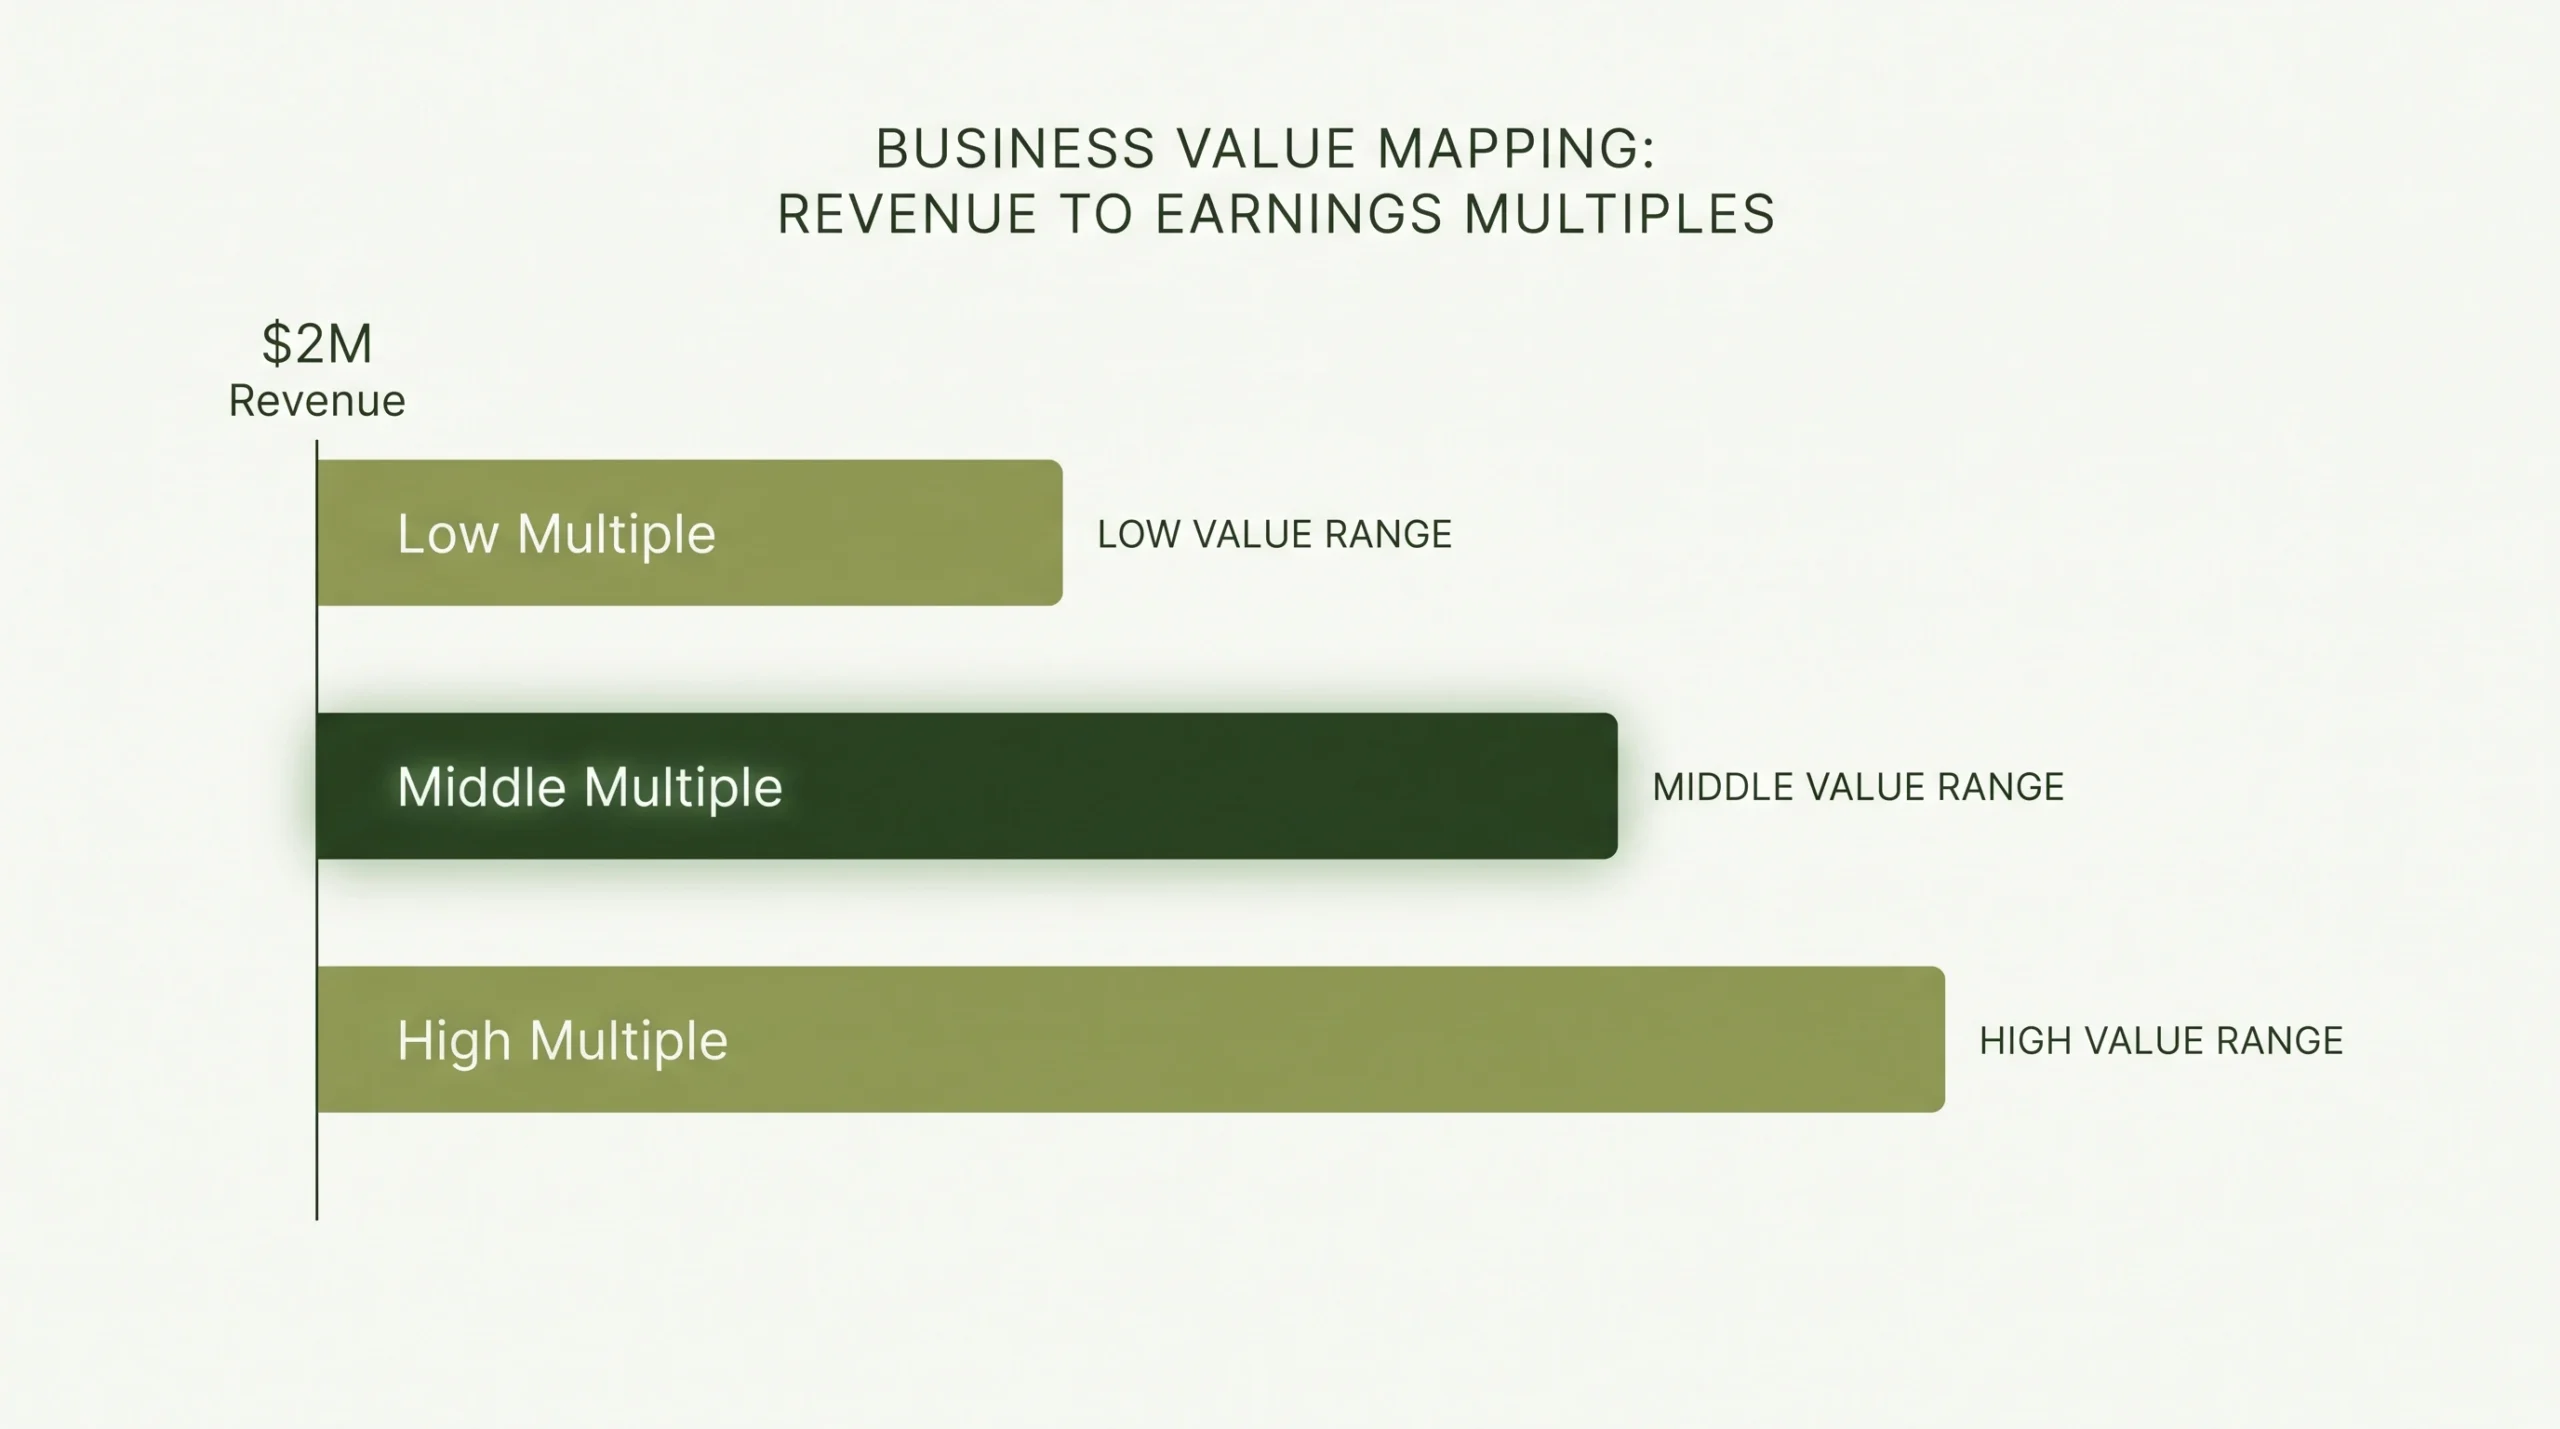
A realistic value range for a $2 million business is roughly $600,000 to $6 million. The number rests on margin and risk. Say a service firm earns 10 percent, or $200,000. A three times multiple puts its worth near $600,000. A high-margin software firm earning 40 percent, or $800,000, may reach eight times. That lifts the figure toward $6 million. These examples are illustrative, not a promise.
Wide as that spread sounds, it reflects real deal evidence. Profit efficiency, growth, and stability all pull the figure up or down. A firm with recurring revenue and low customer concentration sits near the top. One that leans on a single owner or a few clients sits lower. This is why revenue alone is a poor guide. The same $2 million in sales can support a very different price, based on the earnings and risk behind it.
Should You Use SDE or EBITDA?
The right basis depends on size and how the business runs. Smaller owner-run firms use Seller’s Discretionary Earnings, or SDE, which adds the owner’s pay back into profit. Larger firms use EBITDA, which measures core operating profit without owner benefits. At $2 million in revenue, the choice hinges on whether an owner still works in the business day to day. Both turn one year of profit into a value estimate.
| Basis | What it measures | Best suited to | Common range |
|---|---|---|---|
| SDE | Owner’s total yearly benefit | Owner-run firms | 2x to 4x |
| EBITDA | Core operating profit | Larger, manager-run firms | 4x to 8x |
| Revenue | Gross sales | Quick screen only | 0.5x to 3x |
Notice how far the revenue multiple can swing. That range is so wide because it ignores cost and risk. A profit multiple gives a tighter, more honest read. For a firm at this size, the basis often shifts as the owner steps back. The adjusted EBITDA vs EBITDA distinction matters once a company grows large enough to run without its founder present.
How Do Owner Add-Backs Change Earnings?
Owner add-backs change earnings by restoring costs that are personal, not part of the business. This step is called normalization. Appraisers recast your profit to show what the firm really earns for any owner. The goal is a clean number a buyer can trust. Common add-backs include an above-market salary, a family member on payroll, and one-time legal fees. Each one raises the earnings base that the multiple is applied to.
Here are typical items that get added back:
- Owner pay above a fair market wage for the role
- Personal costs run through the business, such as a car or travel
- One-time expenses that will not repeat, like a lawsuit or a move
These adjustments often raise reported profit by a wide margin. A firm showing $300,000 in net income might reveal $450,000 in true earnings once this step is done. That change can lift the final value by six figures. Careful, well-documented add-backs are one of the biggest levers in any deal, which is why normalized earnings sit at the heart of a defensible report.
How Does Industry Change the Multiple?
Industry changes the multiple because each sector carries its own risk and growth outlook. Buyers pay more for steady, hard-to-copy earnings. A software firm with recurring revenue may trade at six to eight times profit. A local service shop with the same profit may sell for three to four times. The gap reflects how sure a buyer feels about next year’s income. Two owners with equal earnings can walk away with very different checks.
Growth prospects and margins shape the spread further. High-margin firms with loyal customers hold their value in a downturn. Project-based firms, such as a builder, swing with each contract, so buyers apply a discount. Standards like IRS Revenue Ruling 59-60 direct appraisers to weigh these industry conditions, not just the raw earnings. Sofer Advisors checks your sector against current market data, so the multiple fits the real world your firm competes in. The result reflects your business, not a generic average.
Which Valuation Methods Do Appraisers Use?
Appraisers use three methods: the market approach, the income approach, and the asset approach. Each views the company from a different angle. The market approach compares your firm to similar businesses that recently sold. The income approach, often the capitalization of earnings method, converts steady profit into value. The asset approach totals what the business owns, less what it owes. A sound valuation weighs all three, then blends them into one figure.
For a firm at $2 million in revenue, the market and income approaches usually carry the most weight. The final number must hold up for its purpose, whether a sale, a tax filing, or a partner buyout. This is where The Sofer Difference shows: a four-phase process of Discovery, Diligence, Analysis, and Delivery that yields an audit-ready report. Large firms such as Alvarez and Marsal or Kroll aim at enterprise clients. Sofer Advisors brings that same senior-level rigor to middle-market owners, and unlike a solo practitioner, backs each conclusion with a full W2 team of 14. The work follows USPAP and AICPA SSVS standards, so the result stands up to review.
Frequently Asked Questions
How much is a business worth with $2 million in sales?
A business with $2 million in sales is usually worth $600,000 to $6 million, based on profit. Revenue alone is a weak guide, since a dollar of sales is not a dollar of earnings. A high-margin firm with recurring income sits near the top. A thin-margin or owner-dependent firm sits lower. Sofer Advisors weighs your true earnings, industry risk, and balance sheet to reach a defensible figure.
How much profit should a $2 million business make?
There is no fixed rule, though firms with $2 million in revenue often net 5 to 30 percent, based on sector. A high margin points to a scalable, efficient model. A thin margin suggests heavy overhead or a capital-intensive operation. What counts for value is the normalized profit, not the reported figure. David Hern CPA ABV ASA and his team check your margin against peers of similar size and risk.
What is a good EBITDA margin for a $2M business?
An EBITDA margin of 15 to 25 percent is often strong for a firm this size. It shows tight control of operating costs relative to sales. A margin below 10 percent may signal pricing pressure or a high cost base that cuts value. Higher margins usually earn a higher multiple, since they point to lasting earnings. Sofer Advisors compares your margin to industry data to spot changes that could raise your value.
How much is a business worth with $1 million in profit?
A business with $1 million in profit often sells for three to eight times that amount. The final multiple depends on growth, margins, and how much risk a buyer sees. A steady, hard-to-copy firm earns a premium. One facing decline or heavy competition earns a discount. The three valuation approaches, weighed together, produce a range that a real buyer, lender, or court would accept as defensible.
Does customer concentration lower the value of a $2M business?
Customer concentration lowers value because it raises risk. When one client drives a large share of sales, losing that client could sink future income. Buyers know this, so they discount the price to cover the danger. A firm with a broad, stable client base earns a higher multiple than one that leans on a single account. An appraiser reviews your sales mix to measure how much this risk pulls value down.
How does recurring revenue affect value?
Recurring revenue raises value because it makes future cash easier to predict. Contracts and subscriptions let a buyer forecast earnings with more certainty. That lower risk supports a higher multiple. A firm built on one-off jobs must win new work each month, so buyers pay less for it. Sofer Advisors reviews your revenue quality in every job, since repeat income often drives a large part of enterprise value.
How long does a valuation take?
A formal business valuation usually takes four to eight weeks. The timeline depends on how complex your financials are and the purpose of the report. It covers data review, market research, and the study needed to hold up under review. Simple planning work moves faster. Deals, tax matters, and disputes need deeper study. Sofer Advisors manages this through its Discovery and Analysis phases and works to meet your required deadline.
Can I value my business on revenue alone?
Valuing a business on revenue alone is rarely accurate. Top-line sales ignore the costs, debt, and risk that decide real worth. A revenue multiple can swing widely, since it says nothing about profit. For a sale, a tax filing, or a dispute, that gap becomes a real problem. A profit-based analysis, weighed against market data, produces a number that survives review by a buyer, the IRS, or a court.
How much does a business valuation from Sofer Advisors cost?
A full business valuation from Sofer Advisors typically runs $7,500 to $25,000. The price depends on how complex your books are and the scope of the report. Simpler planning or tax work may fall toward the lower end. Deals and litigation support need deeper analysis, so they fall higher. Contact Sofer Advisors for a fee quote matched to your situation and goals.
Related Case Studies
- EBITDA Add-Backs: What Buyers Accept and What They Reject
- Mid-Market M&A Due Diligence Checklist: 14 Categories Buyers Review
- Guideline Public Company Method: Comp Sets
Executive Summary
A business with $2 million in revenue is typically worth $600,000 to $6 million, driven by profit rather than sales. A low-margin service firm earning $200,000 may sell near three times, or $600,000. A high-margin software firm earning $800,000 may reach eight times, near $6 million. These figures are illustrative. Add-backs can lift reported profit by six figures. Industry sets the multiple, since recurring earnings command more than project-based work. A sound valuation weighs the market, income, and asset approaches under IRS Revenue Ruling 59-60, USPAP, and AICPA SSVS. Sofer Advisors brings this rigor through a full W2 team and 180+ five-star Google reviews.
What Should You Do Next?
Start by gathering three to five years of tax returns, plus a current profit and loss statement. Next, normalize your earnings so owner perks and one-time costs do not distort the picture. Then confirm the purpose of the work, since a number for planning may not survive IRS or court review.
For a value you can defend, work with David Hern CPA ABV ASA. His team has given expert witness testimony in 11+ cases across Georgia, Florida, California, and New Mexico. Schedule a consultation to discuss what your $2 million business is really worth.
People Also Read
- Owner Compensation Normalization: Why Salary Affects Sale Value
- Customer Concentration: Why It Cuts Sale Price 10 to 30 Percent
About the Author
This guide was prepared by David Hern CPA ABV ASA, founder of Sofer Advisors, a business valuation firm headquartered in Atlanta, GA serving clients across the United States. David holds dual accreditations as an Accredited Senior Appraiser (ASA) and is Accredited in Business Valuation (ABV), credentials recognized by the IRS, SEC, and FINRA. He also holds the Certified Exit Planning Advisor (CEPA) designation. With 15+ years of valuation experience, David has served as an expert witness in 11+ cases across multiple jurisdictions and built Sofer Advisors into an Inc. 5000-recognized firm with 180+ five-star Google reviews. Its full W2 employee team maintains subscriptions to all major valuation databases and operates under a next business day response policy. For professional business valuation services, visit soferadvisors.com/about-us/ or contact Sofer Advisors at soferadvisors.com/contact-us/.
Disclaimer: This content is for informational purposes only and does not constitute professional valuation advice. Business valuation conclusions depend on specific facts and circumstances. Contact Sofer Advisors for guidance regarding your specific situation.