

Last Updated: September 2026
An annual ESOP valuation is the yearly, independent appraisal ERISA requires for a private company owned by an Employee Stock Ownership Plan. A qualified, independent appraiser sets the fair market value of the shares at least once a year, and again for each transaction. That value drives account balances, share allocations, and the price the plan pays to buy or cash out stock. The typical yearly engagement runs six to ten weeks.
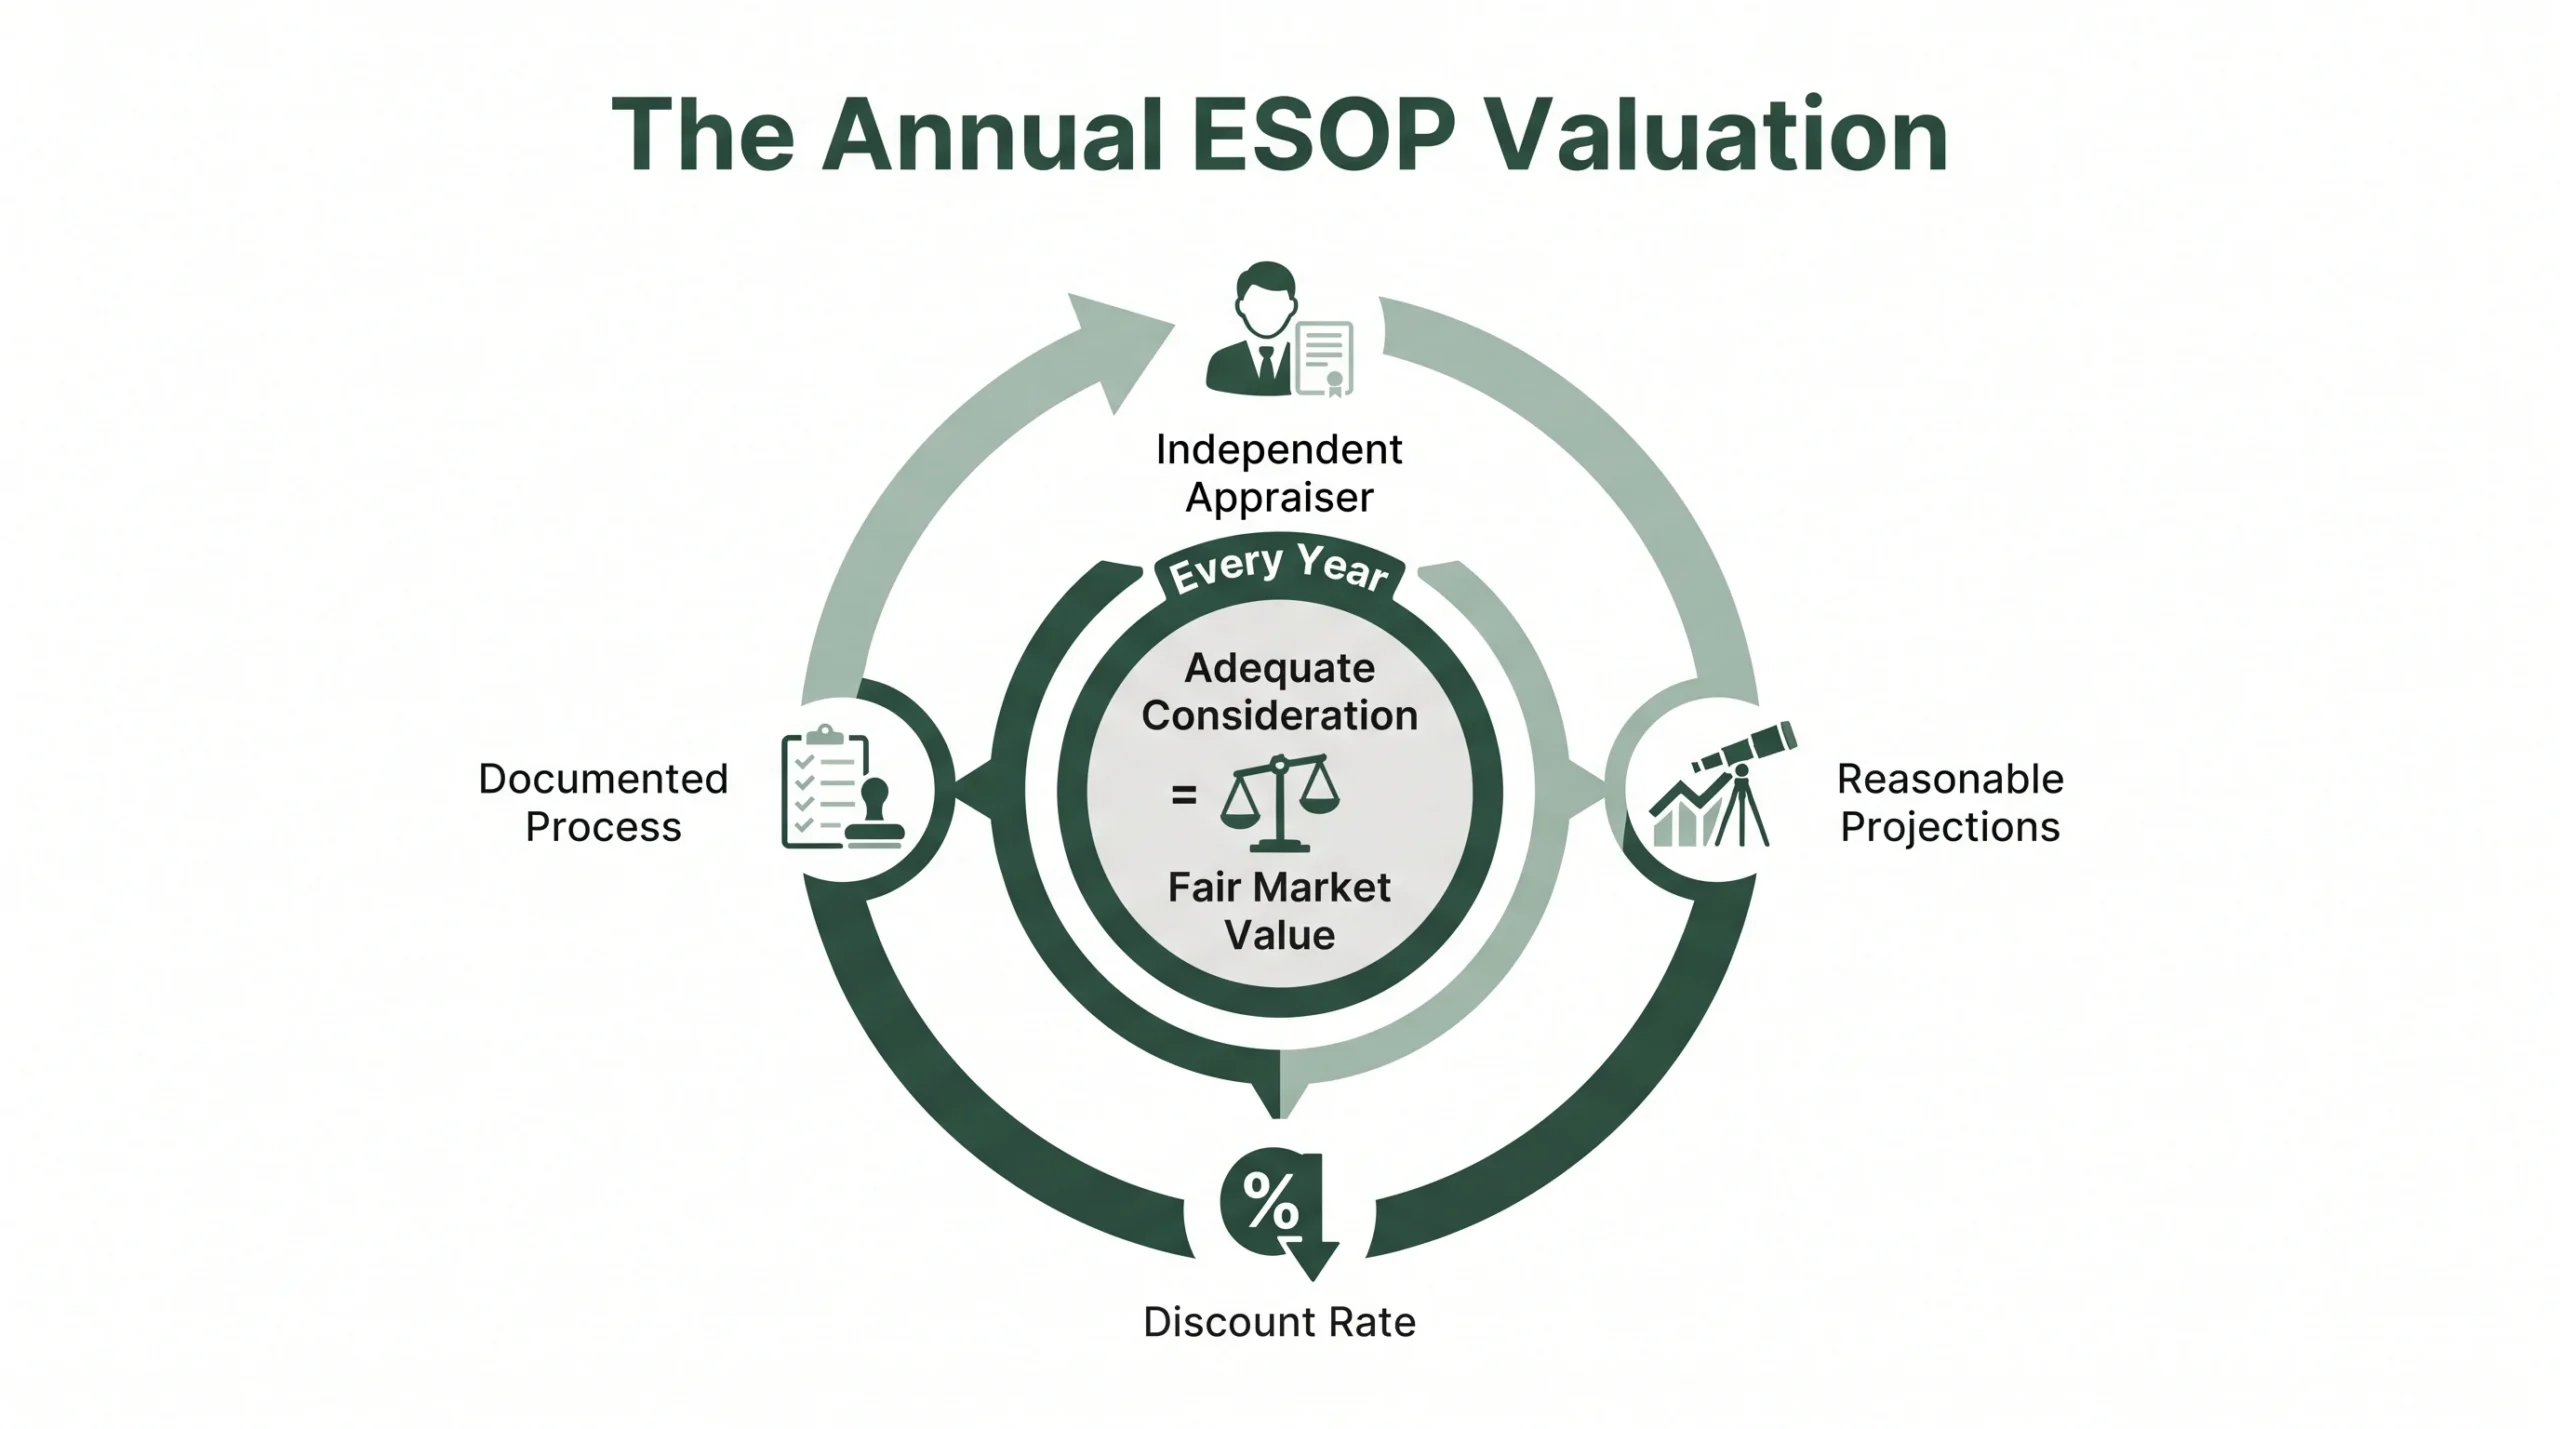
The number carries real legal weight. Adequate consideration is the fair market value standard under ERISA. The trustee must meet it so the plan never overpays for company stock. The Department of Labor enforces that standard. A weak or inconsistent valuation is a common target when the DOL or participants raise questions, so the yearly report has to stand on its own.
Sofer Advisors provides independent, defensible valuations for privately held and family-owned businesses nationwide. The firm applies recognized professional standards to complex ownership structures. Its record includes 180+ five-star Google reviews and 11+ expert witness cases. Its senior team holds dual credentials, ABV and ASA, both recognized by the IRS, SEC, and FINRA.
Key Takeaways
- Yearly is the floor: ERISA requires an independent appraisal at least once a year, and again for each transaction the plan makes.
- Adequate consideration means fair market value: the trustee must make sure the plan pays no more than that value, set in good faith.
- The trustee owns the fiduciary duty: the trustee hires and oversees the appraiser and signs off on the value the plan uses.
- The DOL checks the process, not just the price: independence, projections, the discount rate, and documentation all get reviewed.
- It is recurring: the annual valuation is separate from the one-time valuation at the plan’s formation, and it repeats every year.
These points shape how a plan stays compliant and how owners avoid costly missteps. The sections below explain what the law requires, what adequate consideration means, and what a defensible report looks like.
What is an annual ESOP valuation?
An annual ESOP valuation is a yearly opinion of the fair market value of company stock held by the plan. An independent, qualified appraiser prepares it as of the plan’s fiscal year-end. The trustee uses that value to update accounts, allocate shares, and price repurchases when employees leave. The work reviews earnings, cash flow, the balance sheet, and market comparables. It then applies the income, market, and asset approaches as the facts require.
The valuation is not a formality. It sets the price at which real dollars move between the company, the plan, and departing employees. Because the shares have no public market, the appraiser must estimate fair market value from the business itself. Our guide to the fair market value standard explains how a willing buyer and seller frame that estimate.
Why does ERISA require a yearly ESOP valuation?
ERISA requires a yearly valuation because the plan holds an asset with no public price. The Department of Labor’s Employee Benefits Security Administration administers ERISA. The statute directs that employer stock held by a plan be valued at least annually by an independent appraiser. Without a fresh yearly number, the plan could not fairly credit accounts or set a defensible repurchase price.
The yearly cadence protects employees. Their retirement accounts rise and fall with the share value, so the figure must reflect current performance. A stale or self-serving value would shortchange retiring participants and expose the company to claims. Current appraisals keep the plan honest and give the trustee a record to stand behind.
What does adequate consideration mean for an ESOP?
Adequate consideration means the plan pays no more than fair market value, set in good faith, when it buys company stock. ERISA section 3(18) sets this standard. It is the core test the trustee must meet. When the ESOP buys shares, adequate consideration caps the price. When a participant is cashed out, fair market value sets the payout. The plan and its members should never overpay or be underpaid.
Good faith is the part owners often miss. The DOL reads adequate consideration to require both a fair price and a sound process behind it. The agency’s adequate consideration regulation remains proposed and is not final as of 2026. So best practice draws on court decisions and the settlement process agreements that shaped fiduciary conduct. Because these are legal duties, owners and trustees should consult ERISA counsel rather than treat any article as advice.
What does the DOL and trustee check in the valuation?
The DOL and trustee check the appraiser’s independence, the reasonableness of projections, the discount rate, and how control and marketability are treated. They also look for consistency with the prior year and a documented, arm’s-length process. The point is to confirm the value is credible and reached in good faith, not reverse-engineered to fit a desired price. The table below lays out the main review points.
| Review area | What is checked | Why it matters |
| Appraiser independence | No financial stake in the outcome; hired and overseen by the trustee | A conflicted appraiser undermines the whole report |
| Management projections | Are forecasts supportable and tied to real history | Rosy projections inflate value and risk overpayment |
| Discount rate | Does the rate match the risk of the business | A low rate lifts value; a high rate cuts it |
| Control and marketability | Discounts fit the plan’s actual ownership and put rights | Wrong treatment skews the price up or down |
| Process and records | Documented, arm’s-length steps and prior-year consistency | Good faith is proven by the paper trail |
Each area builds toward one question: would a careful, unconflicted buyer reach this value? Independence keeps the number neutral. Grounded projections keep it honest. The right discount rate and correct discounts keep it fair to the plan and the seller. A clean record shows good faith. A strong ESOP report is built around these points, so it answers the DOL’s questions before they are asked.
How is the annual valuation different from the formation valuation?
The annual valuation administers an existing plan, while the formation valuation prices the first sale of stock to the ESOP. At formation, the appraiser supports a single, high-stakes transaction, and the trustee negotiates the seller’s price. After that, the yearly valuation keeps the plan running: it updates accounts, sets allocations, and prices repurchases. Both must meet fair market value, but they serve different moments.
Owners often confuse the two because both use the same standard. The formation deal is a one-time event with its own diligence, and our overview of the ESOP transaction process walks through those steps. The annual engagement is the recurring duty most owners miss. It arrives every year and feeds directly into repurchase planning. Firms weighing a sale can compare paths in our transaction advisory work.
Which valuation provider fits an ESOP engagement?
Owners usually choose among independent valuation firms, large advisory practices, and generalist accountants. All can produce a number, but ESOP work rewards independence and a defensible process. Large firms such as Alvarez & Marsal, Stout, and Kroll serve the biggest plans. Middle-market companies often want senior attention and a report tuned to DOL review. The table compares the common options.
| Provider type | Service focus | Fit for a recurring ESOP |
| Sofer Advisors | Independent, defensible opinion of value | Strong; senior-level work sized for the middle market |
| Large advisory firm | Enterprise plans and complex deals | Good for the largest plans; higher cost and layers |
| Generalist accountant | Tax and compliance filings | Limited; rarely built for DOL-grade valuation |
Independence is the deciding factor. The trustee hires the appraiser, and that appraiser must have no stake in the price. This follows The Sofer Difference, a four-phase method of Discovery, Diligence, Analysis, and Delivery, with a Heart of a Teacher approach that keeps owners informed. Sofer Advisors keeps the valuation function separate from any deal role, applies USPAP and AICPA valuation standards, and subscribes to all major valuation databases. That gives trustees a report they can defend and employees a value they can trust.
The questions below cover what owners and trustees ask most.
Frequently Asked Questions
How is an ESOP valuation calculated?
An ESOP valuation is calculated by estimating the fair market value of company stock using the income, market, and asset approaches. The appraiser weighs earnings, cash flow, comparable companies, and the balance sheet, then applies discounts or premiums that fit the plan’s ownership. Because the shares have no public market, the value comes from the business itself. The result must reflect a willing buyer and willing seller acting with full knowledge.
What is adequate consideration for an ESOP?
Adequate consideration is fair market value determined in good faith, the price cap the plan must respect when it buys company stock. ERISA section 3(18) sets the standard, and the Department of Labor enforces it. In practice it means both a fair number and a sound process behind that number. The plan should never pay more than the shares are worth, and departing participants should be cashed out at that value.
Why does an ESOP need a valuation every year?
An ESOP needs a yearly valuation because the plan holds stock with no public price, and employee accounts must reflect current value. ERISA requires an independent appraisal at least annually, and again for each transaction. The fresh number updates account balances, sets allocations, and prices repurchases fairly. A stale value would shortchange retiring participants and expose the company to claims, so the appraisal repeats every year.
Who selects the ESOP appraiser?
The trustee selects and oversees the appraiser, because the trustee is the ERISA fiduciary responsible for the value the plan uses. The appraiser must be independent and qualified, with no financial stake in the outcome. Company management may provide data and projections, but it does not control the conclusion. This separation protects participants and helps the trustee show the value was reached at arm’s length and in good faith.
What does the DOL look for in an ESOP valuation?
The DOL looks for appraiser independence, supportable projections, a reasonable discount rate, and control and marketability treatment that fits the plan’s ownership. It also checks for consistency with prior years and a documented, arm’s-length process. The agency reviews the quality of the analysis and the good faith behind it, not just the final figure. A clear record showing careful, unconflicted work is what withstands that review.
What is the ESOP 25% rule?
The ESOP 25% rule refers to the IRS limit on how much a company can deduct for contributions to the plan, generally up to 25% of eligible participant payroll each year under Internal Revenue Code section 404. Debt-financed ESOPs have added rules for deducting loan payments. The limit shapes how quickly a plan can be funded, but it is a tax matter, separate from the fair market value the appraiser sets.
How do I know how much my ESOP is worth?
You know your ESOP’s worth from the most recent annual valuation prepared by the independent appraiser and accepted by the trustee. That report states the fair market value per share and the total plan value as of the fiscal year-end. Participants receive a yearly statement showing their account balance based on that figure. For a full picture of value drivers, an independent review of the business itself helps.
Is the annual valuation the same as the valuation at ESOP formation?
No, the annual valuation is not the same as the formation valuation. The formation valuation prices the first sale of stock to the plan, a one-time transaction with its own diligence and negotiation. The annual valuation keeps the existing plan running by updating accounts and pricing repurchases each year. Both meet fair market value, but the yearly engagement is a recurring duty that continues for the life of the plan.
How much does an annual ESOP valuation cost?
An ESOP valuation from Sofer Advisors runs $15,000 to $35,000, with a typical timeline of six to ten weeks. Because ERISA requires it every year, most companies plan for the annual valuation as a recurring cost, not a one-time expense. The fee depends on company size, deal activity, and complexity. For a quote tied to your plan, request an ESOP valuation estimate with your financials.
Related Case Studies
- ESOP Transaction Process Steps: Complete Guide for Business Owners
- ESOP Feasibility Study: Is Your Business a Good Candidate?
- ESOP Tax Benefits: What Owners and Employees Gain
Executive Summary
ERISA requires a private ESOP company to have its stock valued by an independent, qualified appraiser at least once a year, and again for each transaction. That yearly value updates employee accounts, sets allocations, and prices repurchases. The trustee must ensure the plan pays no more than adequate consideration, the fair market value set in good faith under ERISA section 3(18). The Department of Labor reviews appraiser independence, projections, the discount rate, control and marketability treatment, and the process. This recurring engagement, priced at $15,000 to $35,000, is distinct from the one-time formation valuation. Sofer Advisors delivers reports built to withstand that review.
What Should You Do Next?
Confirm your plan’s fiscal year-end and calendar the annual valuation so it never runs late. Engage an independent, qualified appraiser through the trustee, keep projections supportable, and save the records that show an arm’s-length process. Because these are fiduciary and legal duties, work with ERISA counsel on the trustee’s obligations, and treat the yearly valuation as a standing budget item.
David Hern CPA ABV ASA, founder of Sofer Advisors, provides independent, defensible valuations built for DOL review. Schedule a consultation to discuss your plan.
People Also Read
- How to Calculate Fair Market Value of a Company: Expert Guide
- Business Exit Planning Strategies Guide for Owners in 2025
About the Author
This guide was prepared by David Hern CPA ABV ASA, founder of Sofer Advisors, a business valuation firm headquartered in Atlanta, GA serving clients across the United States. David holds dual accreditations as an Accredited Senior Appraiser (ASA) and is Accredited in Business Valuation (ABV), credentials recognized by the IRS, SEC, and FINRA. He also holds the Certified Exit Planning Advisor (CEPA) designation. With 15+ years of valuation experience, David has served as an expert witness in 11+ cases across multiple jurisdictions and built Sofer Advisors into an Inc. 5000-recognized firm with 180+ five-star Google reviews. Its full W2 employee team maintains subscriptions to all major valuation databases and operates under a next business day response policy.
For professional business valuation services, visit soferadvisors.com/about-us/ or contact Sofer Advisors at soferadvisors.com/contact-us/.
Disclaimer: This content is for informational purposes only and does not constitute professional valuation advice. Business valuation conclusions depend on specific facts and circumstances. Contact Sofer Advisors for guidance regarding your specific situation.









